How to Divide Debt After Divorce: A Step-by-Step Guide

Learn how to divide debt after divorce, including marital vs. separate debt, state rules, and practical steps to protect your credit and implement

Table of Contents

Last Updated: October 14, 2026

Understanding Marital Debt vs. Separate Debt

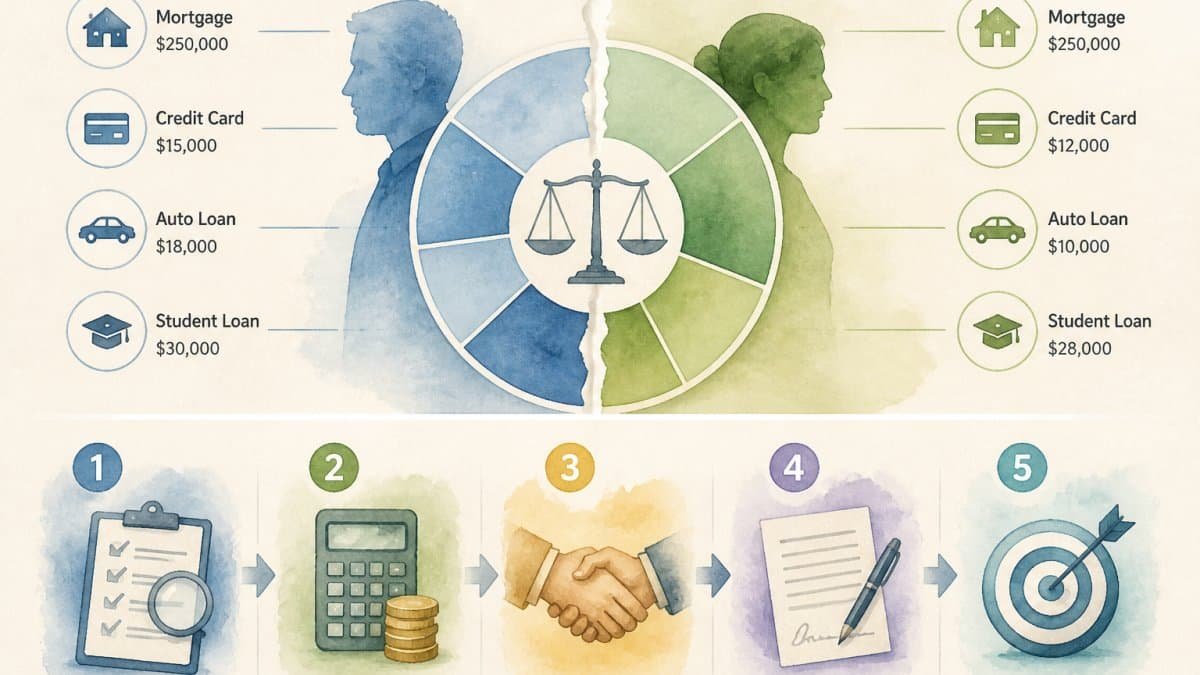
When you divide debt after divorce, first determine which debts belong to both spouses and which belong to one person alone. This distinction shapes how courts and settlement agreements handle what you owe.

Marital debt is any debt incurred during the marriage for the benefit of the marriage or family: credit card charges for household expenses, medical bills, car loans for family vehicles, and home mortgages.

Separate debt belongs to one spouse alone: debts incurred before marriage, debts accumulated after legal separation, student loans taken out by one person for their own education, and debts explicitly kept separate by agreement. It typically stays with the person who incurred it.

The line between these categories determines who pays what after the divorce is final. Some debts are mixed: a credit card opened before marriage but used for family groceries during the marriage might fall into both categories.

Pro Tip
Ask your attorney to review each debt account statement from the marriage date. Document the opening date, purpose, and balance at separation. This paper trail becomes crucial in settlement negotiations and court proceedings.

How Courts Classify and Divide Debt in Divorce

Courts use two main frameworks depending on where you live: community property and equitable distribution.

In community property states, courts treat all marital debt as jointly owned, regardless of whose name is on the account, and typically split it 50/50. These states include Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin.

In equitable distribution states, courts divide marital debt fairly but not necessarily equally, considering each spouse’s income, earning capacity, financial circumstances, and who benefited from the debt. This applies in the remaining states.
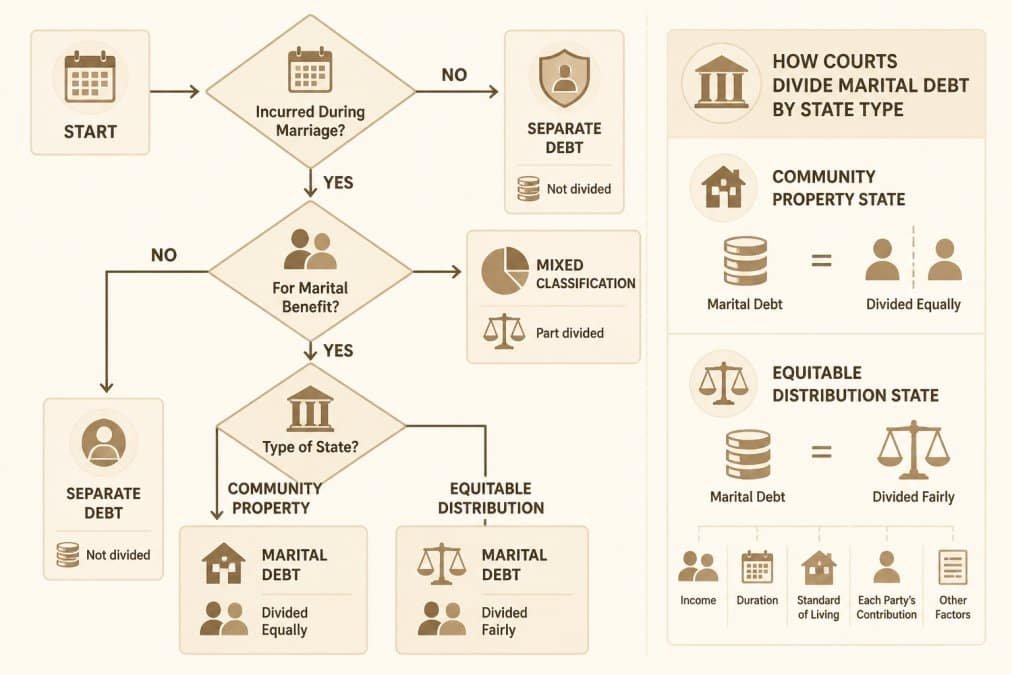
Flowchart showing debt classification decision tree: Is debt incurred during marriage? Was it for marital benefit? Community property state or equitable distribution state? Courts examine several factors when classifying and allocating debt: - **Who incurred the debt?** Did one or both spouses sign? - **When was it incurred?** Before, during, or after the marriage? - **What was it for?** Family benefit, one person's benefit, or unclear? - **Who benefited?** Did both spouses gain? - **Current finances?** Can both spouses afford to pay? A mortgage on the marital home is almost always marital debt, even if only one spouse signed the note, as are credit card debt for family vacations and a car loan for a vehicle both spouses used. :::warning Courts can order one spouse to pay a debt in the spouse's name, but creditors are not bound by the divorce decree. If your ex's name is on the account and they don't pay, creditors can pursue you. You remain liable until the debt is refinanced or paid off. ::: ## Who Is Responsible for Debt After Divorce Responsibility and legal liability are different. The divorce decree assigns who should pay, but creditors follow the original loan agreement, not the court order. If your name is on the account, you remain legally responsible to the creditor even if the decree says your ex should pay, true for credit cards, auto loans, mortgages, and any joint obligation. Your agreement can require your ex to indemnify you, pay and hold you harmless, but enforcement requires going back to court. Many people end up paying debts their ex was supposed to handle because the creditor doesn't recognize the decree. The solution is removing your name from accounts. Until you remove your name, the debt affects your credit score and your ability to borrow. Lenders see you as responsible for the full amount, regardless of what the divorce decree says. :::takeaway Your divorce decree protects you against your ex in family court. It does not protect you against creditors. Refinancing debts into one spouse's name is the only way to fully separate your financial obligations. ::: ## Creating a Divorce Debt Settlement Agreement A strong debt settlement agreement is specific, realistic, and protects both spouses. It goes beyond "you pay this, I pay that." It includes timelines, refinancing steps, and what happens if someone fails to pay. Start by listing every marital debt: - Creditor name and account number - Current balance - Interest rate - Monthly payment - Who will pay (spouse A or spouse B) - Timeline for payoff or refinancing - Who refinances the account into their name alone Assign clear responsibility for each debt. Include a deadline for refinancing joint accounts. Most financial advisors recommend 30 to 90 days after the divorce is final. Longer delays leave both spouses exposed to credit risk. Address what happens if someone doesn't pay. Also specify how you'll handle joint accounts during separation. Some couples freeze joint credit cards to prevent new charges; others split new charges 50/50. Document the agreement in writing, even if you're not yet divorced. Have an attorney review your settlement agreement before you sign. State law varies on what courts will enforce, and a good agreement prevents disputes later. ## Debt Division Divorce Examples: Common Scenarios Real situations show how debt division works in practice, depending on state law, the couple's finances, and the specific debts involved. **Scenario 1: Home with Mortgage and Home Equity Line of Credit** Sarah and Tom bought a house for $400,000 during their marriage. **Scenario 2: Credit Card Debt from Marital Spending** During the marriage, Mike and Jennifer accumulated $35,000 in credit card debt across four cards, two in each name, all for family expenses. In an equitable distribution state, the court might assign $17,500 to each spouse. **Scenario 3: Student Loan Debt** Alex took out $80,000 in student loans before marriage. During the 10-year marriage, Alex's earning capacity increased significantly because of the degree. The court might order Alex to pay the full loan but assign other assets to the spouse to offset the benefit. In other states, student loans remain separate debt entirely, regardless of when they were incurred or who benefited. ## How to Protect Your Credit During Divorce Your credit score takes a hit during divorce, especially if joint accounts remain open or debts go unpaid. Protecting it requires action before the divorce is final and after. **Before the divorce is final:** - Pull your credit report from all three bureaus (Equifax, Experian, TransUnion) ([Free Credit Reports
Flowchart showing debt classification decision tree: Is debt incurred during marriage? Was it for marital benefit? Community property state or equitable distribution state? Courts examine several factors when classifying and allocating debt: – **Who incurred the debt?** Did one or both spouses sign? – **When was it incurred?** Before, during, or after the marriage? – **What was it for?** Family benefit, one person’s benefit, or unclear? – **Who benefited?** Did both spouses gain? – **Current finances?** Can both spouses afford to pay? A mortgage on the marital home is almost always marital debt, even if only one spouse signed the note, as are credit card debt for family vacations and a car loan for a vehicle both spouses used. :::warning Courts can order one spouse to pay a debt in the spouse’s name, but creditors are not bound by the divorce decree. If your ex’s name is on the account and they don’t pay, creditors can pursue you. You remain liable until the debt is refinanced or paid off. ::: ## Who Is Responsible for Debt After Divorce Responsibility and legal liability are different. The divorce decree assigns who should pay, but creditors follow the original loan agreement, not the court order. If your name is on the account, you remain legally responsible to the creditor even if the decree says your ex should pay, true for credit cards, auto loans, mortgages, and any joint obligation. Your agreement can require your ex to indemnify you, pay and hold you harmless, but enforcement requires going back to court. Many people end up paying debts their ex was supposed to handle because the creditor doesn’t recognize the decree. The solution is removing your name from accounts. Until you remove your name, the debt affects your credit score and your ability to borrow. Lenders see you as responsible for the full amount, regardless of what the divorce decree says. :::takeaway Your divorce decree protects you against your ex in family court. It does not protect you against creditors. Refinancing debts into one spouse’s name is the only way to fully separate your financial obligations. ::: ## Creating a Divorce Debt Settlement Agreement A strong debt settlement agreement is specific, realistic, and protects both spouses. It goes beyond “you pay this, I pay that.” It includes timelines, refinancing steps, and what happens if someone fails to pay. Start by listing every marital debt: – Creditor name and account number – Current balance – Interest rate – Monthly payment – Who will pay (spouse A or spouse B) – Timeline for payoff or refinancing – Who refinances the account into their name alone Assign clear responsibility for each debt. Include a deadline for refinancing joint accounts. Most financial advisors recommend 30 to 90 days after the divorce is final. Longer delays leave both spouses exposed to credit risk. Address what happens if someone doesn’t pay. Also specify how you’ll handle joint accounts during separation. Some couples freeze joint credit cards to prevent new charges; others split new charges 50/50. Document the agreement in writing, even if you’re not yet divorced. Have an attorney review your settlement agreement before you sign. State law varies on what courts will enforce, and a good agreement prevents disputes later. ## Debt Division Divorce Examples: Common Scenarios Real situations show how debt division works in practice, depending on state law, the couple’s finances, and the specific debts involved. **Scenario 1: Home with Mortgage and Home Equity Line of Credit** Sarah and Tom bought a house for $400,000 during their marriage. **Scenario 2: Credit Card Debt from Marital Spending** During the marriage, Mike and Jennifer accumulated $35,000 in credit card debt across four cards, two in each name, all for family expenses. In an equitable distribution state, the court might assign $17,500 to each spouse. **Scenario 3: Student Loan Debt** Alex took out $80,000 in student loans before marriage. During the 10-year marriage, Alex’s earning capacity increased significantly because of the degree. The court might order Alex to pay the full loan but assign other assets to the spouse to offset the benefit. In other states, student loans remain separate debt entirely, regardless of when they were incurred or who benefited. ## How to Protect Your Credit During Divorce Your credit score takes a hit during divorce, especially if joint accounts remain open or debts go unpaid. Protecting it requires action before the divorce is final and after. **Before the divorce is final:** – Pull your credit report from all three bureaus (Equifax, Experian, TransUnion) ([Free Credit Reports

(https://consumer.ftc.gov/articles/free-credit-reports)). Check for errors or accounts you don’t recognize.

  • Freeze joint credit cards to prevent new charges. Get written agreement from your ex about this step.
  • Set up automatic payments on joint debts so payments don’t get missed during the divorce process.
  • Open a credit card or line of credit in your name alone to establish individual credit history.
  • Document all agreements about debt responsibility in writing.

After the divorce is final:

  • Refinance joint accounts into one spouse’s name immediately. Don’t wait.
  • Monitor the refinanced accounts to ensure the responsible spouse is paying on time.
  • Update your credit report with the divorce decree. Credit bureaus should reflect the new account ownership.
  • If your ex’s name is still on an account after 60 days, contact the creditor and provide a copy of the divorce decree.
  • Check your credit report monthly for the first year after divorce. Look for accounts your ex was supposed to pay that show late payments or defaults.

If your ex fails to pay a debt assigned to them, you have options:

  • Pay the debt yourself to protect your credit, then sue your ex for reimbursement.
  • Contact the creditor and explain the situation. Some creditors will negotiate a payment plan or settlement.
  • Go back to family court and ask the judge to enforce the debt assignment or modify the order.

A late payment on a joint account affects both spouses’ credit scores, even if the decree assigned it to one person, which is why refinancing is so important.

Key Takeaway
Refinancing joint debt into one spouse’s name alone is the only way to fully separate your credit. Until you refinance, late payments or defaults damage both spouses’ credit scores.
Infidelity recovery courses, free quizzes, and tools for healing after betrayal

Implementing Your Debt Division Plan After the Decree

Once the divorce is final and you have a settlement agreement or court order, implementation is the hard part. Many people get the agreement right but fail to execute the refinancing and payment steps.

Create a checklist with specific dates:

  • Week 1: Provide your ex with copies of the final divorce decree and settlement agreement. Confirm they understand their debt assignments.
  • Week 2-4: Contact each creditor holding joint debt. Request refinancing forms and explain that you need to separate the accounts.
  • Week 4-8: Complete refinancing applications. Some take 30 days to process. Have the responsible spouse apply to refinance into their name alone.
  • Week 8-12: Once refinancing is approved, provide the creditor with a copy of the divorce decree. Request that they remove the other spouse from the account.
  • Week 12+: Monitor the account for 60 days. Confirm that the responsible spouse is making payments on time and that the other spouse is no longer listed.

For accounts that can’t be refinanced (some older mortgages, for example), work with your ex to find alternatives. You might sell the asset, pay off the debt, and split proceeds.

Document everything: refinancing requests, approval letters, payment confirmations, and communications with your ex. If your ex fails to pay, you’ll need proof of their responsibility and your enforcement efforts.

If your ex is uncooperative or unreliable, consider paying the debt yourself and pursuing legal remedies later. Protecting your credit is more important than trying to force your ex to pay.

Many people benefit from working with a financial advisor or mediator during this phase. After the Affair Series provides structured frameworks for managing difficult conversations, especially when an ex is hostile or resistant to cooperating on financial matters.

Conclusion

Dividing debt after divorce requires understanding your state’s laws, classifying each debt correctly, and taking concrete steps to refinance and separate accounts. The divorce decree assigns responsibility, but creditors follow the original loan agreement. Your name on an account means you remain legally liable, regardless of what the court ordered.

Start by listing all marital debt, assigning responsibility clearly, and setting firm refinancing deadlines. Protect your credit by monitoring accounts, setting up automatic payments, and confirming joint accounts are separated. If your ex fails to pay, be prepared to pay the debt yourself and pursue remedies through family court.

The goal is a clean financial separation, your debts in your name, your ex’s debts in theirs, and no lingering joint obligations. This takes time and persistence, but it’s the only way to move forward with financial stability and peace of mind.

Frequently Asked Questions

How is debt divided in a divorce?

Debt division depends on your state’s laws and the specific debts involved. In community property states, marital debt is split equally; in equitable distribution states, courts divide debt fairly based on factors like income, earning capacity, and financial circumstances. Separate debt (incurred before marriage or after separation) typically remains with the spouse who incurred it. The divorce decree assigns responsibility, but creditors are not bound by it, you must refinance or pay off jointly held debt to fully protect yourself.

What happens if my ex does not pay debt assigned to them in the divorce decree?

A divorce decree assigns responsibility between spouses but does not release either party from creditor liability. If your ex fails to pay joint debt, creditors can pursue you for the full balance. You can file a contempt motion against your ex for violating the decree, but this requires court action and time. The best protection is to refinance joint accounts into your ex’s name alone, sell property securing the debt, or pay off the balance yourself before finalizing the divorce. Document all non-payment in writing for potential enforcement later.

Can a divorce decree remove my name from a joint loan?

No. A divorce decree cannot remove your name from a joint loan without the lender’s consent. Creditors are not bound by divorce agreements. To remove your name, you must refinance the loan in your ex’s name alone, or pay off the balance. For mortgages, this typically requires a refinance or sale of the home. For credit cards and other debts, contact the creditor to request removal, though most will not agree unless your ex qualifies on their own income and credit. Until the debt is refinanced or paid off, you remain liable.

How can I protect my credit during and after a divorce?

Separate joint accounts immediately by closing or freezing them, then opening individual accounts in your name only. Request that your ex refinance joint debt into their name or agree to pay it off before the divorce is final. Monitor your credit report monthly for unauthorized activity or missed payments by your ex. Include specific payment deadlines and refinancing timelines in your settlement agreement. If your ex fails to pay assigned debt, creditors will report late payments to your credit file, you may need to pay the debt yourself and pursue reimbursement through the court. Consider a credit freeze to prevent identity theft during the separation.

pinit fg en rect red 28

Author

  • S. J. Howe

    S.J. Howe, a counsellor with over twenty years of experience, specialises in helping couples navigate infidelity, betrayal, and relational trauma. Together, they blend lived experience with therapeutic expertise to guide readers through every stage of healing.

Scroll to Top